
Design a life you love.
Fee-only, fiduciary financial life design. We start with the life you want, then build the plan and the portfolio that support it.
Fee Only.
No commissions, ever.
Fiduciary.
Legally required to act in your interest.
20 Minutes.
First call, no pitch.
What our clients say about us
Client testimonial received via Wealthtender. Testimonials were provided by current Mana clients and may not be representative of the experiences of other clients. The clients were not compensated, nor are there material conflicts of interest that would affect the given testimonials. You can view a complete list of all reviews here.
We help people like you navigate life’s transitions with confidence.
Founders & Early Employees
You've spent years building. Your equity position is growing, and so are the questions keeping you up at night. We build the plan now, so you're ready for the windfall.
Multi-Generational Families
Kids leaving the nest. Parents aging. We guide the hard conversations, and help you feel good about your choices along the way.
Pre & Recent Retirees
You did the saving. The voice in your head still says not yet. We provide a clear financial plan, so you can confidently spend on the life you spent decades saving for. See how we help you live your best life.
We want you to feel really good about your money.
Sell the business, buy the house, retire without looking back. Our financial life design process starts with listening to what matters most to you. Then, we create a plan that balances real life with your vision for the future.
Our process
Fit Meeting
We listen to what brings you here and share how we work.
Introduction
We organize your full picture and put your goals on paper.
Life Design
We set the money aside and picture the future you want.
Investments
We review your portfolio and set a goals-based strategy.
Financial Life Plan
We bring it all together and focus on the next one to two years.
What you can expect from working with us:
Annual Updates & Ongoing Partnership
Each year, we revisit your goals, net worth, cash flow, investments, risk management, and long term projections. Once your plan is in place the work deepens. Mana becomes your first call for anything that touches your financial life, and we reshape your plan together as your life evolves.
The financial life plan covers
Tax Planning
Insurance
Retirement
Investment Analysis
Estate Planning
Education Planning
Employee Benefits
Real Estate
Stock Compensation
Account Optimization
Charitable Giving
Career Planning
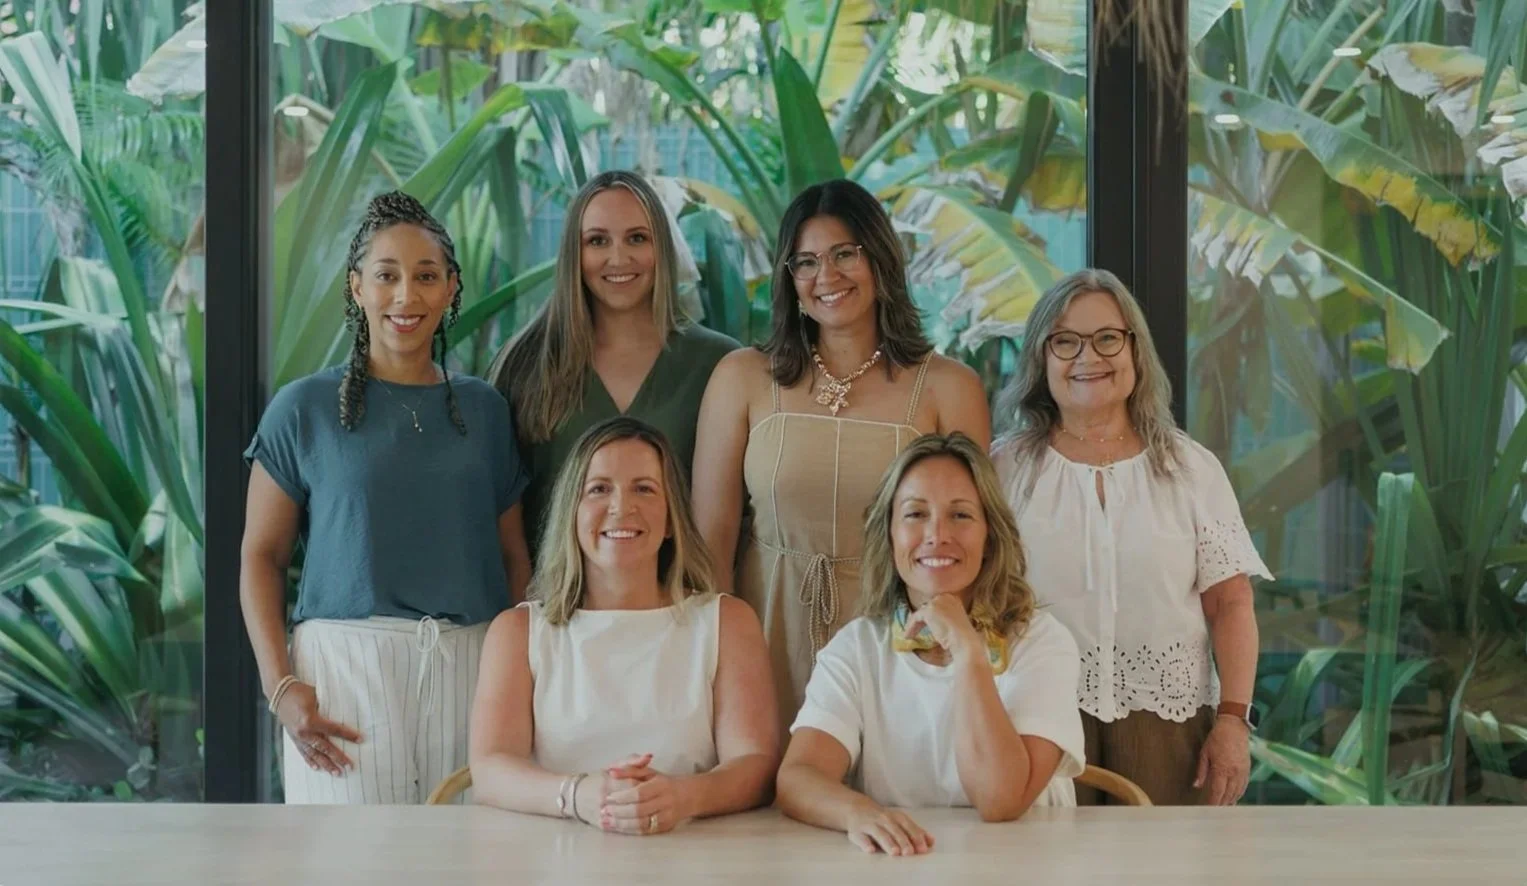
Get to know our amazing team
Given the choice of living for more, or living for meaning, we are drawn to those who choose the latter.

- ✓ Certified Financial Planner®
- ✓ Registered Life Planner®

- ✓ Certified Public Accountant
- ✓ Chartered Financial Analyst®


- ✓ Graduate Certificate in Personal Finance
- ✓ Certified Financial Planner®

We’re paid by you. That’s it.
We’re proud to be fiduciaries, which means no commissions. No hidden fees. We’re required to act in your best interest. See our FAQs for more detail.
Financial advice for your whole life. Not just your bottom line.
Simple answers to the questions we hear most
-
Financial Life Design is how we do financial planning at Mana. Most firms start with your portfolio, which is a little like designing a house by picking out the furniture first. We start with your life, the richest and most honest version of it you can imagine, and then we build the tax, investment, and planning strategy that supports it.
-
We build globally diversified portfolios on a few durable beliefs: that markets are broadly efficient, that costs and taxes are among the few things we can actually control, and that disciplined rebalancing is worth more than trying to predict what happens next. We design each portfolio around your whole financial picture, including real estate, private investments, and equity compensation, and around how you want your money invested. From there we adjust as your needs evolve, coordinating investment decisions with tax planning, cash flow, and charitable giving.
-
There isn't one number, and a firm that gives you one is describing a portfolio that probably isn't yours. We run models for clients with simpler situations and we track those, but even their real results drift from model results because of timing, cash flows, and rebalancing. Our portfolios are built around return targets, risk capacity, risk tolerance, income needs, and whatever else is already in the picture: concentrated stock, real estate, private investments, or a particular tax situation. Blending all of that into an average would tell you very little about what to expect.
What we can do is be specific. We use JP Morgan's long-term capital market assumptions for planning projections, and once we understand your situation we can tell you what we're targeting and why. Every holding has a job. For example, money for a tax bill next spring may sit in Treasuries, while money for a retirement that's thirty years out is in global stocks. If you want income, stability, or returns that don't track the market, we can lean into alternatives, an area Stephanie spent years in as a risk manager at the world's largest publicly traded hedge fund. What we measure ourselves on is whether you reach your goals.
-
We do not prepare or file tax returns. What we do is tax strategy, and it runs through everything: multi-year projections, equity compensation timing, Roth conversion windows, charitable giving, and how withdrawals are sequenced in retirement. We work alongside your CPA so the strategy and the return line up, and if you don't have a CPA, we'll help you find one.
-
The most common thing we see isn't a bad decision, it's no decision. The stock has done well and selling feels like giving up on it. Or it's down and selling feels like locking in the loss. Or you're in a leadership role and holding feels like part of the job. So nothing happens, often for years, while the position quietly grows into most of your net worth.
We start by naming what the position actually is: what share of your net worth, what your cost basis looks like, what would have to be true for holding to be the right call, and what a 40% decline would actually do to your plan. Then we build something. Sometimes that's a multi-year sell-down sequenced around your tax brackets, executed through a 10b5-1 plan if you're an insider. Sometimes it's diversifying around the position with direct indexing rather than selling it. Sometimes it's a collar or a protective put to put a floor under the downside, a pledged asset line for liquidity without triggering a tax bill, or a charitable vehicle if giving is already part of your picture. Sometimes it's setting price targets in advance so the decision is made before the moment arrives.
And sometimes it's holding. If you have the capacity to take the risk and you want to take it, that's a real choice and we'll help you size it. What we're after is the difference between choosing to hold and never getting around to anything else.
-
It depends on what you're saving for, which is why there's no single right answer. Education, a first home, and giving a kid a financial head start all point to different account types with different tax and control tradeoffs. We've written about this in depth, so start here: Family Planning & Kids on the Mana blog.
-
Yes. We have some clients who enjoy trading and are good at it, and we'd rather you do it in a defined space than not tell us about it. What we ask is that it's a separate account, that it's sized so a bad year doesn't change your plan, and that we can see what's in it.
That last part matters more than it sounds. If you're buying the same tech names we're deliberately underweighting to offset your equity comp, the diversification we built on paper isn't real. If you're harvesting losses on our side while buying the same fund on yours, you've triggered a wash sale and the tax benefit disappears. None of that is a reason not to trade. It's a reason for us to know.
-
We become the hub of your financial team. That means we're in regular contact with your CPA, estate attorney, insurance agent, and lender, so the people advising you are working from the same picture instead of each seeing one piece. In practice it looks like bringing your estate attorney into a conversation as your estate changes shape, or getting ahead of a concentrated stock or option exercise question with your CPA well before a filing deadline forces the decision.
-
Our fee has two parts. The Financial Life Design fee covers the planning relationship and starts at $10,000 a year. Investment management is billed separately on the assets we manage, starting at 0.75% on the first $1 million and stepping down from there. There is some flexibility in the planning fee for clients with larger portfolios, since the two pieces are related, and we always tell you your exact all-in fee in writing before you decide anything.
The first conversation is free. And different.
20 minutes. No pitch.
Just an honest look at whether we’re the right fit.